Telecom infrastructureWholesale
The Great Wholesale Reset: From Moving Traffic to Governing Outcomes
MEF Keynote, April 14, 2026
Matteo Gatta11 min read
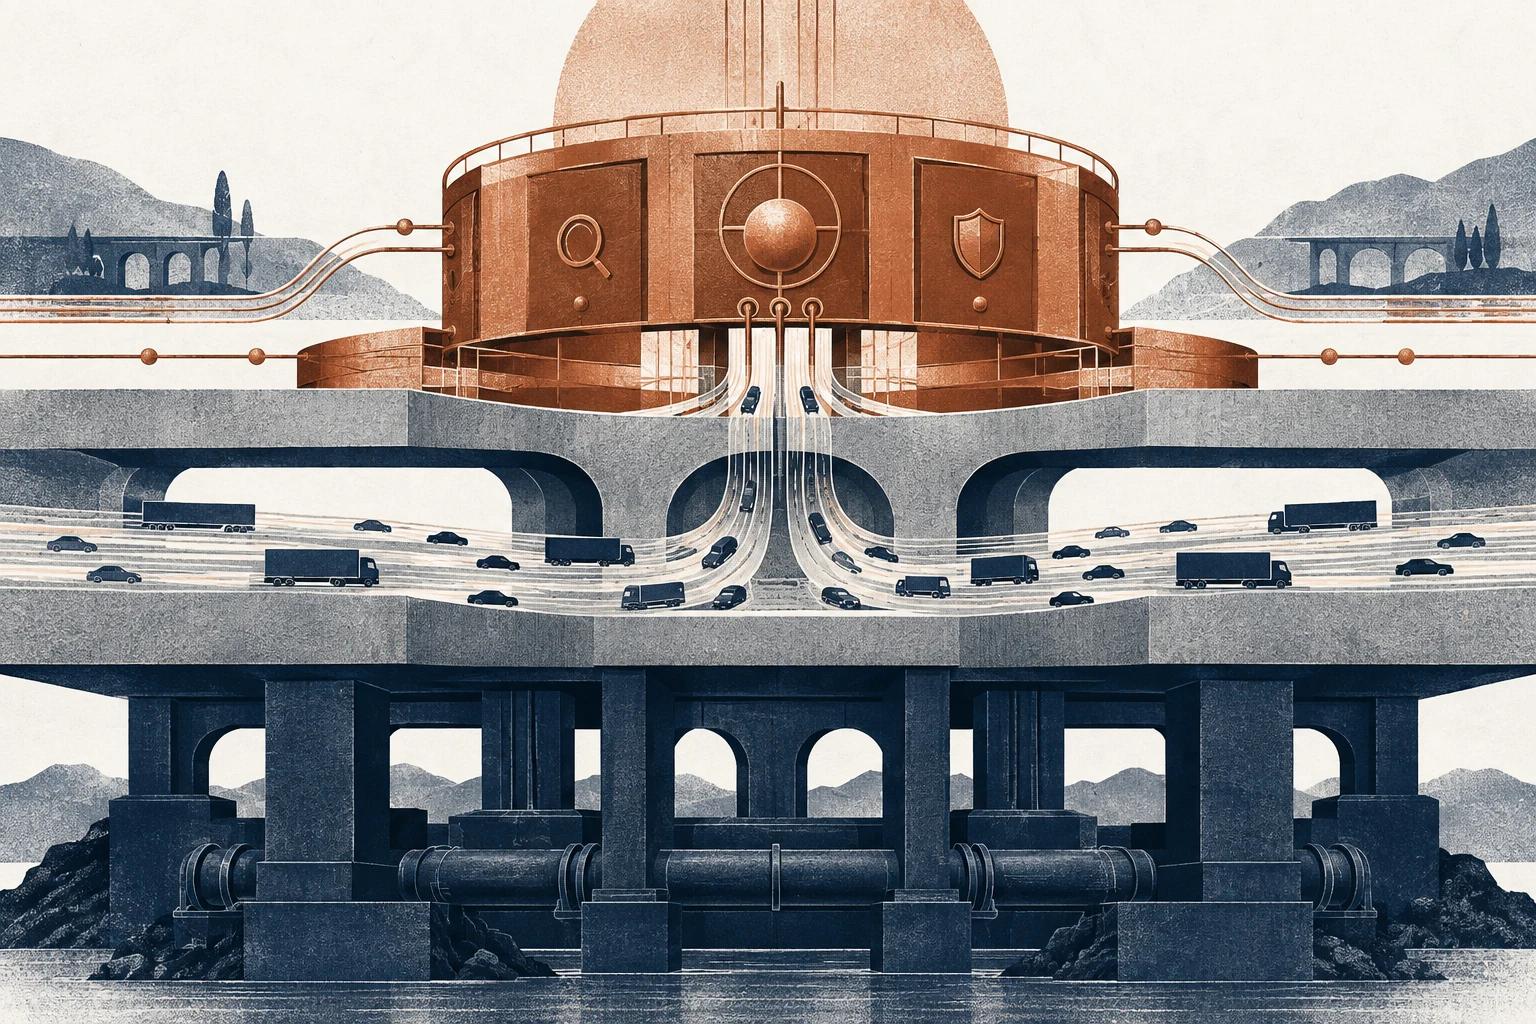
The most dangerous place in wholesale right now is the middle. Not the infrastructure layer. Not the application layer. The middle — where most of us have lived for twenty years. Moving traffic efficiently. Aggregating volume. Connecting supply to demand across borders and protocols.
A large share of legacy wholesale profit pools — in international voice, messaging aggregation, and intermediation — still sits exactly there. That middle is being hollowed out.
Not because the traffic disappears. It won't. But because the value is migrating — upward, toward the systems that decide, verify, and guarantee. And downward, into raw infrastructure that competes on cost alone.
This is the Great Wholesale Reset. And it is not a future scenario. It is already underway.
From Transport to Trusted Traffic
The first pillar of wholesale was transport (voice, IP, IPX, messaging). The logic was straightforward: move bits across borders as efficiently as possible. Optimize routes, manage interconnections, and extract margin from fragmentation. For years, this was enough.
Today, it is not — and the shift is brutally concrete. Wholesale is no longer just about moving traffic at scale. In a world where fraud has overtaken ransomware as CEOs' top concern, the next source of value is not only transport. It is trusted identity, verified interaction, and control.
An enterprise placing international voice calls into a high-value market used to ask two questions: What does it cost? Does it connect? Now it asks a third: Is it trusted?
In markets where call authentication frameworks are enforced, a call without proper attestation is flagged, degraded, or blocked. A cheaper route is irrelevant if the call never reaches the customer — or worse, is labeled as spam before it does.
The economic question has shifted from "How do I route this call?" to "Can I guarantee this call is legitimate?" The pressure is no longer coming only from telecom economics. It is coming from a broader trust crisis, made it worse by the power of AI. In this environment, a route is no longer judged only by cost and quality. It is judged by whether it can preserve trust, protect reputation, and carry traffic that enterprises are still willing to process.
The same logic is dismantling the signaling model. What used to be a question of latency and reliability is now a question of integrity. Operators deal with signaling fraud, location spoofing, and abnormal traffic patterns that scale instantly. The risk is no longer technical. It is financial and reputational.
In that environment, the network cannot remain neutral. Wholesale players that can certify origin, maintain reputation, detect anomalies, and enforce policies in real time move into a different category. They are no longer optimizing routes. They are governing what is allowed to pass.
And the commercial model follows. Value no longer sits in minutes or capacity. It sits in verified call completion, fraud prevented, compliance ensured. Transport is no longer priced as movement. It is priced as assurance.
From Scale to Context
The second pillar was scale. Its peak expression was messaging and CPaaS aggregation. The model was simple: aggregate volume, connect operators to enterprises, benefit from economies of scale. If you handled the most traffic, you had leverage.
Scale was power. But scale, on its own, is no longer defensible. The erosion is not gradual. It is structural.
Industry estimates suggest that a significant share of global A2P traffic shows signs of manipulation. Artificially inflated traffic has siphoned billions from enterprises, sometimes with tacit complicity along the chain. At the same time, SMS-based authentication — the foundation of that volume — is being supplemented and, in some use cases, displaced by number verification APIs, device-based authentication, and app-based models. Once trust in a channel erodes, substitution accelerates.
Scale built on arbitrage is not a moat. -> It is a liability. Scale without context now amplifies risk as much as revenue. Veriff reports that 4.18% of verification attempts in 2025 were fraudulent — roughly one in twenty-five — while digitally altered or AI-generated media rose 300%, and impersonation accounted for more than 85% of attacks.
That changes the commercial logic. Enterprises do not just need reach; they need intelligence that can distinguish a legitimate interaction from a synthetic one, learn from outcomes, and improve with every transaction.
Take a very concrete example: a bank sending one-time passwords used to negotiate on cost per SMS and delivery rates. Today, that same bank is asking entirely different questions. How many authentication attempts fail? How many are intercepted? How much fraud originates from weaknesses in the authentication flow?
A provider that delivers messages competes on price. A provider that combines messaging with number verification, SIM swap detection, device intelligence, and real-time risk scoring sells something else entirely. It sells contextualised authentication.
And authentication is priced per successful verification. Per fraud avoided. Per secure session established. Per outcome.
And the hidden asset in this transition is data. Every authentication check, every delivery confirmation, every conversion signal generates intelligence. Over time, intelligence feeds models that understand fraud patterns, customer behavior, and local context. Because once these models are trained on real interaction data — local fraud patterns, delivery behavior, customer response — they become extremely difficult to replicate. The moat is no longer connectivity. -> It is learned intelligence.
Wholesale players that remain at the level of throughput are pushed down the stack. Those that integrate into workflows — controlling routing logic, identity signals, and outcome feedback — move up.
Scale still matters. But it is no longer the advantage. The advantage is controlling the context in which scale is applied.
From Access to Recognition
The third pillar was access. Built on SIM cards, numbering resources, and roaming agreements. Access was about scarcity — who could enter the network, under what conditions, and at what price.
That scarcity is dissolving. Connectivity is now provisioned in seconds. Roaming, the most captive business in recent times, is finally abstracted. Distribution is digital. The gates are no longer where they used to be.
But access is not disappearing. It is being redefined.
Look at what enterprises actually need. A fintech expanding across markets does not want to negotiate operator by operator. It wants a global identity layer. Numbers that work across geographies. Authentication mechanisms that are reliable. Compliance embedded by design.
This is where telecom assets take on a different meaning. The phone number is no longer just a routing identifier. It is a login credential. A recovery mechanism. A fraud signal. A regulatory anchor.
Before approving a transaction, a bank checks whether a number is active, whether it has recently been reassigned, or whether a SIM swap occurred. These signals determine whether a transaction proceeds or is blocked.
What is being monetized is not connectivity. It is trusted identity. And unlike most digital identity systems, telecom identity is not self-declared. It is regulated, audited, and tied to real-world accountability. That difference is not technical. -> It is institutional.
And in a zero-trust environment, it becomes decisive. Access becomes recognition.
The Decision Layer: Reading the Signal
As transport, scale, and access are redefined, a new architecture is emerging above them. It is the layer that decides.
Where identity is verified. Where policy is enforced. Where decision context is interpreted. Where actions are triggered. The system that determines not just how networks are used, but whether they should be used at all. This is not a future battleground. It is already being claimed. What connects the three pillars — trusted traffic, contextual intelligence, and identity — and elevates the wholesale layer from infrastructure to decision system, is the ability to read the probabilistic intent signals embedded in every transaction.
Wholesale carries billions of transactions across every channel. With guardrails in place — verified identity, authenticated traffic, contextual routing — those transactions stop being movement and become decision context: signals about what an enterprise is trying to accomplish, what risk looks like, what outcome to drive toward.
The signal isn't always declared. A failed authentication attempt indicates risk. A voice call routed through a high-trust path indicates a relationship worth protecting. A message triggered at a precise behavioural moment indicates an opportunity.
The wholesale layer, positioned at the convergence of all these channels, is uniquely placed to read that decision context — and act on it, within the entrusted delegation. A wholesale platform that captures this context can steer outcomes: prioritising the call that should reach its destination, blocking the transaction that should be reviewed, triggering the verification that must happen before the session proceeds. It doesn't just carry transactions. It governs them.
And the compounding logic is this: every governed outcome feeds the next decision. Decision context becomes the fuel for a learning loop. The more transactions flow through a platform that understands probabilistic intent, the more precise and commercially valuable that understanding becomes. The moat is not the network. It is the accumulated intelligence about what the network's traffic means.
Enterprise voice has already shifted. Platforms like Teams and Meet now control routing, policy, and user experience. The underlying infrastructure still carries the traffic.
But the decision does not sit there anymore. The wholesale layer did not disappear. It became infrastructure inside someone else's system. And once that position is lost, it is almost impossible to reclaim. Because control layers, once established, are rarely displaced from below.
The implication is clear. If wholesale does not move up, it will not vanish. -> It will be controlled.
The AI Tailwind: Not To be Missed!
There is a structural shift accelerating outside the wholesale industry.
The SaaS layer that sat above us — CPaaS platforms, contact center vendors, collaboration tools — is being destabilised by AI. Categories built on commodity functionality face structural demand destruction. Per-seat pricing is compressing.
AI agents are replacing entire product categories. What survives is precisely where wholesale already has real proximity and relevance: data infrastructure, identity and trust capabilities, and software embedded in regulated workflows. As enterprise agents proliferate, a growing share will need to authenticate, verify, notify, call, or transact through regulated communications infrastructure. The pipes do not shrink. They multiply. And their value is no longer measured in minutes or messages. It is measured in trust, compliance, and policy enforcement.
AI does not win on data volume alone. It wins on access to relevant, timely, governed signals. That is where wholesale has an opening: it sits in the flow of authentication events, messaging activity, routing outcomes, fraud patterns across multiple markets. This is not a licence to ignore privacy, regulation, or sovereignty. It is the opposite: the value comes from turning those signals into trusted decisioning within strict legal and contractual limits. The compounding advantage is not raw data accumulation. It is operational learning built ona governed control layer.
The Ownership Question: Who Can Actually Lead This Reset
There is a dimension to this transformation that is rarely discussed. Because it is uncomfortable.
The wholesale reset is not only strategic. It is financial and institutional. And it requires a type of stewardship that many current owners are structurally unable to provide. The reset favours owners with risk capacity, strategic patience, and willingness to fund capability building through a period of legacy decline.
Many corporate structures — particularly incumbent telco groups — struggle to provide that consistently. As wholesale business escapes the old price-times-volume logic, investors do not always understand the new sources of value creation. The result is skepticism that only stubborn, self-referential leaders choose to ignore.
Capital is allocated through cycles. Trade-offs. Internal competition. In that environment, a wholesale business trying to pivot struggles to compete for attention.
The result is predictable. Underinvestment in new capabilities. Overreliance on legacy cash flows. Hesitation at precisely the moment when decisive action is required.
This transition demands something different. It requires owners who can absorb uncertainty. Sustain investment through declining legacy economics. Back a strategic pivot whose returns are neither immediate nor linear.
Private equity can bring focus and discipline — but only where there is a credible differentiation thesis and patience behind the capital. Growth investors may be drawn to identity, APIs, and orchestration — but only if the direction is clear and the end state believable.
Across all ownership models, one requirement remains constant. -> These businesses need entrepreneurial risk capacity. Capital that takes risk. Boards that understand reinvention. Management teams that build new capabilities while navigating ambiguity. And ecosystems. Because the capabilities required — identity, fraud intelligence, software, data, cloud — must be built, bought, and partnered. Not assumed.
Not every player needs to own the full stack. -> But every player needs to understand where they sit — and whether that position will still exist, not in five years, but tomorrow.
The Bottom Line
The Great Wholesale Reset is a redistribution of power.
We are moving from a model where value was captured by controlling the flow, to one where value is captured by controlling the decision.
And the prerequisite for that decision is context — the probabilistic intent signals embedded in every transaction. Every transaction that flows through a trusted, authenticated, contextually intelligent network carries a signal — about what an enterprise needs, what risk looks like, what outcome to drive toward.
The wholesale layer, if positioned across every channel, is one of the few layers that combines regulated identity, cross-channel reach, and network-grade intelligence at scale. That is not a feature. It is a structural advantage.
Competing on price, volume, and reach is a race to the bottom. In a world of abundant connectivity, there is no scarcity in bandwidth. The scarcity is trust.
And trust does not sit at the bottom of the stack. The industry now faces a choice. Remain in the business of moving traffic. Or step into a different role.
Not as a carrier of transactions. As the system that decides which transactions are allowed to exist, how they are executed, and under which conditions they can be trusted.
In the next cycle, profit will sit less in the traffic itself and more in the right to decide, verify, prioritise, and govern what traffic is allowed to do.
The question is whether wholesale will own that decision — or operate inside a system controlled by someone who does.